
September 28, 2026
What are the alternatives to CoinGate, and which one fits your business?
Read article
A crypto merchant account is your business's account with a crypto payment processor. It is a third thing, not your wallet or your exchange account under a new name. Through it, the processor issues invoices to your customers, sees each payment arrive and credits it to your balance.
To get one, you sign up. A processor that checks its merchants then verifies your company (this is KYB verification) and reviews the project you want to take payments for, which in practice means your website.
Not every processor runs these checks, but in the EU every crypto-asset service provider has been required to since 30 December 2024. How long that takes depends on the processor and on how complete your papers are. Some processors let you test everything while you wait, so the review does not have to stall your work.
A processor that skips these checks can sound like the faster road. Some hosted gateways do let you start without documents, yet one that holds a balance for you can still ask for them later, once a payment is flagged and the money is already on your balance. Before you choose that road, read what accepting crypto through a gateway without KYC really means.
No. You now have three accounts with similar names, and each does a different job:
There is also a setup with no merchant account at all: you run the payment software on your own server, and it watches your own wallet. There is no processor to open an account with, and the software and its upkeep are yours. That trade-off is its own decision, laid out in self-hosting a crypto payment gateway versus plugging into a hosted one.
"Merchant services" is what processors call everything a merchant account switches on. The set varies from one processor to another, but it is built around the same pieces:
Once you know what the account switches on, the next questions are price and setup: what a crypto payment gateway costs and how to connect it to a site.
Not every processor verifies its merchants. At one that does, the details differ, but the path runs in this order:
Steps 3 and 4 are where people get stuck, so the rest of this page is about them.
Every requirement a processor sets comes down to three things:
Each processor writes its own detailed list on top of this. Whether a sole trader without a registered company can apply is one of the points where lists differ, so it is worth asking before you start the form.
Requirements are one half of choosing where to apply. The other half is what each processor will actually cost you, which is what ten crypto payment processors compared by total cost sets side by side.
A processor that holds and moves crypto for clients answers for who those clients are. It checks them for two reasons:
KYC, short for know your customer, checks a person: that you are who you say you are, usually with a photo of your passport and a selfie. It is what an exchange did before it opened your personal account; the details are in why an exchange asks for your ID and how KYC in crypto works.
KYB, short for know your business, checks a company in the same spirit: that it really exists, and who stands behind it.
KYB contains KYC inside it. The owners and directors that KYB turns up are then identified one by one, as people. Say two founders run an online shop registered as a limited company: KYB checks the company against the registry, and then each founder goes through their own identity check.
Processors run the check in their own order and with their own tools. What it has to cover is the same:
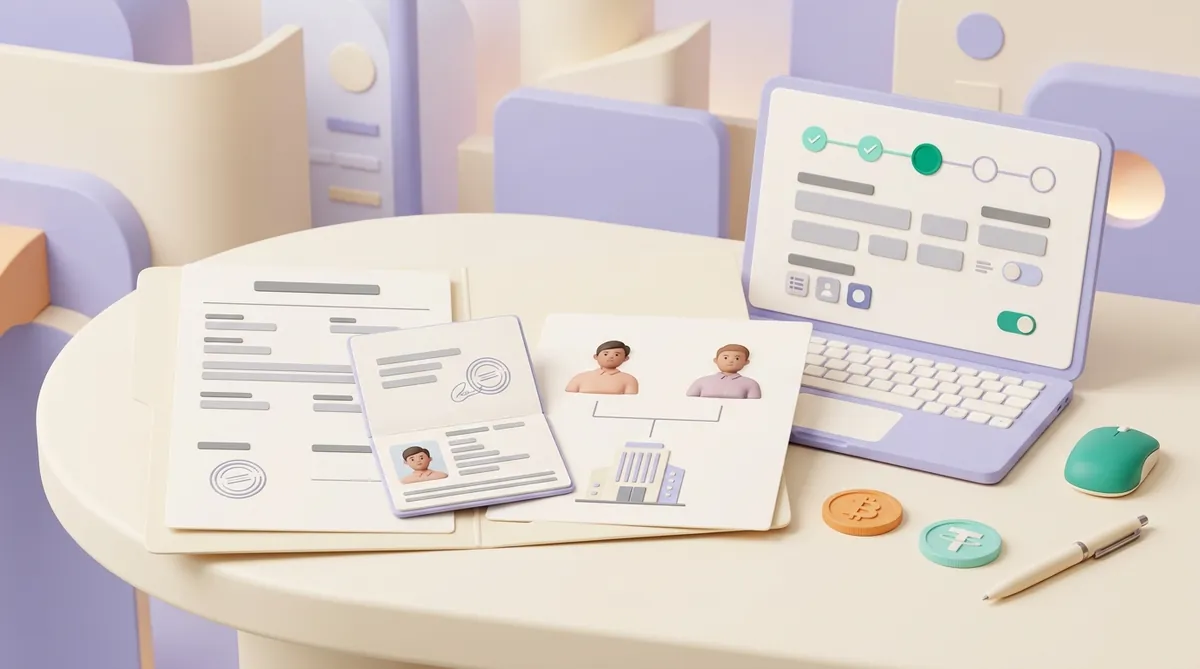
Each paper on the list proves one of the checks above, which makes the set easier to gather once you know what each one is for. The exact documents list is set by the processor and depends on your country:
Before you upload, check that names and numbers match across every paper and the form. A company name spelled one way in the registry extract and another way in the form gets you a follow-up question and a longer wait.
All of these papers assume there is a company to describe. If you sell in your own name and have no registry extract to upload, the check moves to you as a person, and some processors and card gateways sign up sole traders on that basis. Who does, and what they check in place of company documents, is laid out in getting a payment gateway when you have no registered company.
Besides the company, the processor looks at what you will be paid for. That usually means your website, and the reviewer reads it the way a careful customer would:
The site does not have to be finished to a designer's standard. It has to let a stranger understand what the business is and what a customer gets for their money.
If your business is in a category that card acquirers call high risk, such as travel, dating or licensed gambling, this review is where the question comes up with a crypto processor as well. What that status means and how crypto changes it is explained in what a high risk merchant account is and what crypto changes about it.
There is no single number across the industry, because the wait depends on a few things you can predict:
At CryptumPay, the path from sign-up to money on your balance has three steps:
The CryptumPay project review needs a website that shows what you do or sell. The site does not have to be connected: if you take payments only by link, you add no widget and no API integration, but the site still has to be there for the review.
A pending review does not have to be dead time. A few things can move forward in parallel:
A crypto merchant account is a separate account at a processor, built for one job: getting paid by customers. Your wallet and your exchange account stay what they were. Before the processor opens it, it checks your company, the people behind it and the project, so three things are worth doing:
Merchant category codes belong to card networks, and a crypto payment through a processor never passes through them, so a crypto merchant account has no such code. Where cards and crypto do meet, when someone buys cryptocurrency with a card, Visa's rules treat it as quasi-cash, next to foreign currency and money orders. A non-bank business selling crypto for Visa card payments uses code 6051.
It is the identifier a processor gives your account or project. Your site or your API calls send it along, so the processor knows whose invoice it is creating and whose balance a payment lands on. At CryptumPay this identifier is the Project ID, taken from the console, and each project has its own balance.
No. Binance's verification for companies opens a corporate account on the exchange, for trading and holding crypto as a business. Accepting payments from customers is a separate service with its own sign-up and review, wherever you get it. The work is not wasted, though: the same registry extract and owners' IDs will be asked for again.
AML, anti-money laundering, is the goal and the body of rules; KYC and KYB are the tools that serve it. KYC identifies people, KYB identifies companies and the people behind them. In the EU, as of September 2026, the AML directive makes this identification a duty for crypto-asset service providers, which is why a processor cannot skip it.
KYC checks who the customer is, once at the start and again when something changes. KYT, know your transaction, checks the money itself as it moves: each incoming transfer is screened for links to addresses tied to sanctions, hacks or scams. For a merchant, this means a payment from a flagged address can be held for a closer look even after your account is approved.
This article is general information, not legal advice.
Create an account and connect the checkout yourself, or talk to sales and we will plan the integration with you.