
September 20, 2026
Why does my business need a high risk merchant account, and what changes if I start accepting crypto?
Read article
Crypto payment processing fees usually come to about 1% of each payment, the processor's cut. Larger merchants often negotiate less, and some plans add a fixed amount per payment or charge more for high-risk industries. The blockchain network fee is normally paid by the customer, because whoever sends the money pays it.
That 1% is not the whole bill, though. Three more costs sit around it:
Against a typical online card rate in the US of 2.9% plus 30 cents, crypto usually still costs less per payment. How much you save depends on those extras and on how many of your customers actually pay in crypto.
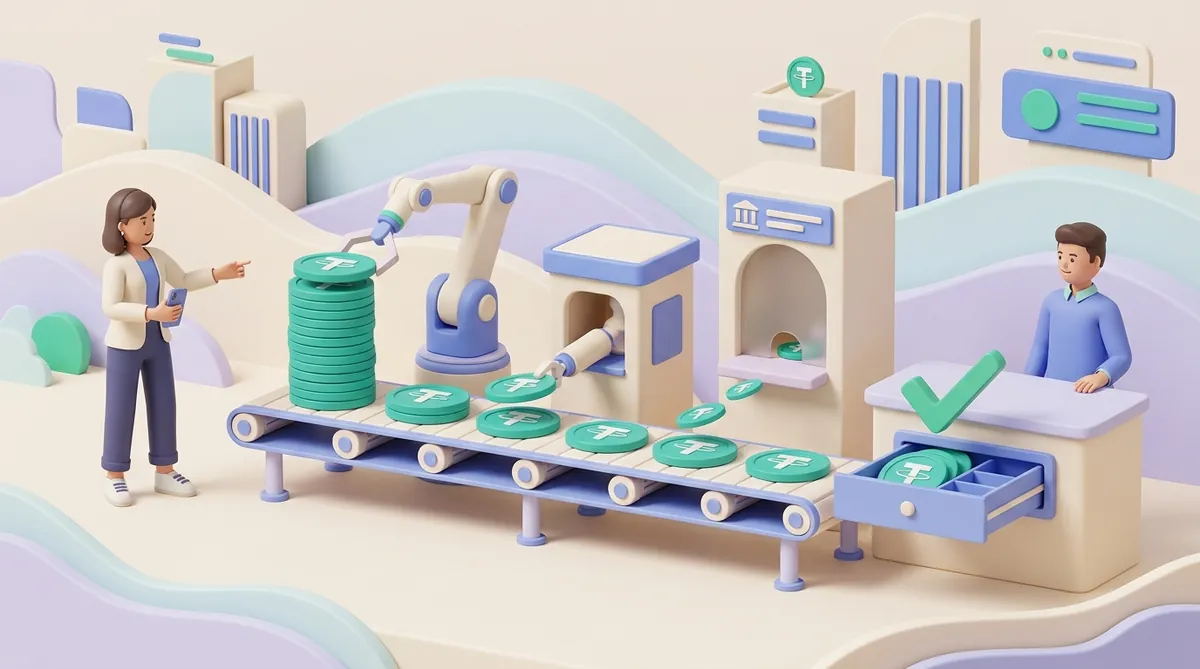
A crypto payment processor is the service that shows your customer the amount and the wallet address, watches the blockchain for the payment and credits your balance. If the route from invoice to your account is new to you, start with how crypto payment processing works for a business from start to finish.
The bill for that service can have up to six lines:
Only some of these lines are the processor's to set:
Most crypto processors publish a flat percentage per payment, and 1% is the most common headline number. On a 200 USDT order that means 2 USDT for the processor and 198 USDT on your balance. USDT is a stablecoin, a token designed to stay worth one US dollar.
The percentage moves with three things:
If you run a gaming or betting site, ask for the price for your category, not the rate on the pricing page. How the cashier and provider fit together there is covered in how crypto payments work for online casinos and sportsbooks.
It also matters when the fee is charged. Some processors take it only on a successful payment, others on every transaction they handle. An expired or abandoned invoice should cost you nothing, and it is fair to ask for that in writing.
The two fees are easy to mix up because both are called a "fee". They pay for different things:
When your customer pays, the customer pays the network fee. Their wallet adds it on top of the amount they send, so the full 100 USDT from the invoice lands on your side. The size of that fee depends on the network and ranges from a fraction of a cent on Solana to a few dollars for a USDT transfer on TRON.
There is one catch. If the customer pays straight from an exchange account, the exchange may deduct its withdrawal fee from the amount, and 99 USDT arrives instead of 100. The processor then marks the payment as underpaid, and someone has to decide whether to ask for the rest or accept it.
You pay network fees yourself whenever you move money out:
Why the same transfer costs pennies on one network and dollars on another is explained in how network fees and gas work on each blockchain.
Fiat is ordinary government money, such as dollars or euros. If your costs are in fiat, received crypto has to be converted at some point, and this is where the bill grows past the headline 1%.
Here is where extra costs usually hide:
A worked example: a customer pays for a 1,000-dollar order in USDT. A 1% processing fee takes 10 dollars, a 1% conversion to dollars takes about 10 more, and a wire payout adds its own charge. The real cost is closer to 2% than 1%, and still below a card.
Each of those charges also goes into the books as its own line. The bookkeeper records the sale at the full 1,000 dollars and the processing fee as an expense, rather than booking only what was left, so the real cost of accepting crypto stays visible. How the conversion and the payout are recorded, and at which rate, is laid out in a bookkeeper's walk-through of a crypto payment from arrival to withdrawal.
Per payment, usually yes. Take a common flat online card rate in the US: 2.9% plus 30 cents per transaction, 1.5% more for an international card and another 1% when currency conversion is needed. Here is how that compares with a 1% crypto fee, plus 1% conversion where the money goes into dollars:
The gap is widest for businesses with many foreign customers, which is why crypto often comes up for subscription software sold worldwide. How it fits next to cards and local methods is covered in the payment stack for a SaaS with international customers.
Cards also carry a cost that does not show in the rate: chargebacks. A chargeback is when the customer asks their bank to reverse a card payment. The merchant usually loses the money and the goods, and pays a separate dispute fee on top. A crypto payment cannot be reversed by the customer's bank, so this cost disappears, and refunds become your decision.
Two things keep the savings smaller than the per-payment numbers suggest:
What changes in checkout, refunds and bookkeeping when a shop adds this option is laid out in what really changes for an online store that accepts crypto.
A pricing page shows the headline rate, and the total sits in the terms. Before you pick a crypto payment gateway, get answers to these questions:
For example, CryptumPay charges 1% per successful payment, from 0.5% on large volumes, and lets the merchant pass the fee on to the customer. Withdrawals from CryptumPay are available at any time with no minimum amount, in manual or automatic mode.
Once you want these questions answered for specific services, see ten crypto processors compared by total cost.
The cheapest payment is the one routed to the method that costs you least, without losing the customer. These steps work for cards and crypto together, and each has its limit:
Adding a charge for a payment method is called surcharging, and it is regulated. The rules below are those in force as of September 2026.
Card-network surcharge rules are about cards. A fee added to a crypto payment is still a fee for a means of payment, so in the EU and the UK it must not exceed what that payment costs you.
A crypto processor typically takes about 1% of each payment, and the customer pays the network fee when sending. What you pay after the money arrives can bring the real cost closer to 2%.
That is still usually less than cards, and crypto payments carry no chargebacks. The savings apply only to the share of customers who pay in crypto, so compare total cost, not the headline rate.
Chargebacks belong in that total. On the card side, each one costs the sale, the goods and a separate fee, and a merchant with too many of them can face a higher rate or a closed account. Before you compare, it helps to know what a single chargeback really costs a merchant.
It depends on the network and how busy it is at that moment. On bitcoin, the fee rises when many people send at once, because transfers compete for limited space in each block. Stablecoin transfers on cheaper networks usually cost from a fraction of a cent to a few dollars, which is why merchants tend to list those networks first at checkout.
You can't avoid them entirely while accepting payments online, because every method has a cost somewhere. A direct bank transfer skips the card processor, but the time your team spends matching transfers to orders is a cost too. A realistic goal is a lower total, not zero.
A card fee is made of three parts:
As of September 2026, the EU and the UK each cap interchange on consumer cards at 0.2% of the payment for debit and 0.3% for credit, but only when the customer's bank and the merchant's bank are in the same region. A card from elsewhere, including a UK card paying through an EU merchant's bank, falls outside the cap and usually costs more. Flat-rate plans bundle all three parts into one number.
Yes: you can publish your own wallet address and take payments directly. No processor takes a percentage, but everything a processor automates lands on your team, starting with working out which transfer paid for which order. The network fees on refunds and withdrawals remain either way.
This article is general information, not legal or tax advice. Check the rules that apply to your business with a qualified adviser.
Create an account and connect the checkout yourself, or talk to sales and we will plan the integration with you.

