
May 20, 2026
Recurring Crypto Payments for SaaS: Renewals, Top-Ups, and Saved Payment Flows
Read article

For most SaaS companies selling abroad, the answer is a card payment processor or a merchant of record, plus one or two extra methods for the customers that cards don't reach. The real decision is the first one. Do you want to be the seller in every country, charging and filing its sales tax and VAT yourself? Or do you pay a higher fee to a company that resells your product and does that work for you?
The short version: a small team selling to people and small businesses all over the world usually does better with a merchant of record such as Paddle. A B2B product with larger invoices and someone who can run tax usually does better with a payment processor such as Stripe. Bank transfers, local payment methods and stablecoins are additions to either one, not replacements.
A customer types a card number into your checkout. The payment processor passes it to the customer's bank through Visa or Mastercard and asks for approval. If the bank says yes, the money lands in your processor balance and reaches your bank account a few days later.
You will also meet the words "payment gateway": that is the part that collects card details securely and hands them to the processor. With Stripe, the gateway and the processor are one company, which is why people use the words interchangeably.
A subscription adds a second layer, the billing system. It remembers each customer's plan, creates an invoice every month or year, charges the saved card and decides what to do when a charge fails. Stripe Billing, Chargebee and the billing built into Paddle all do this job.
Then comes tax. Selling software to a person in another country often means charging that country's VAT or sales tax, and someone has to calculate it, collect it and file it. Who that someone is decides which option suits you.
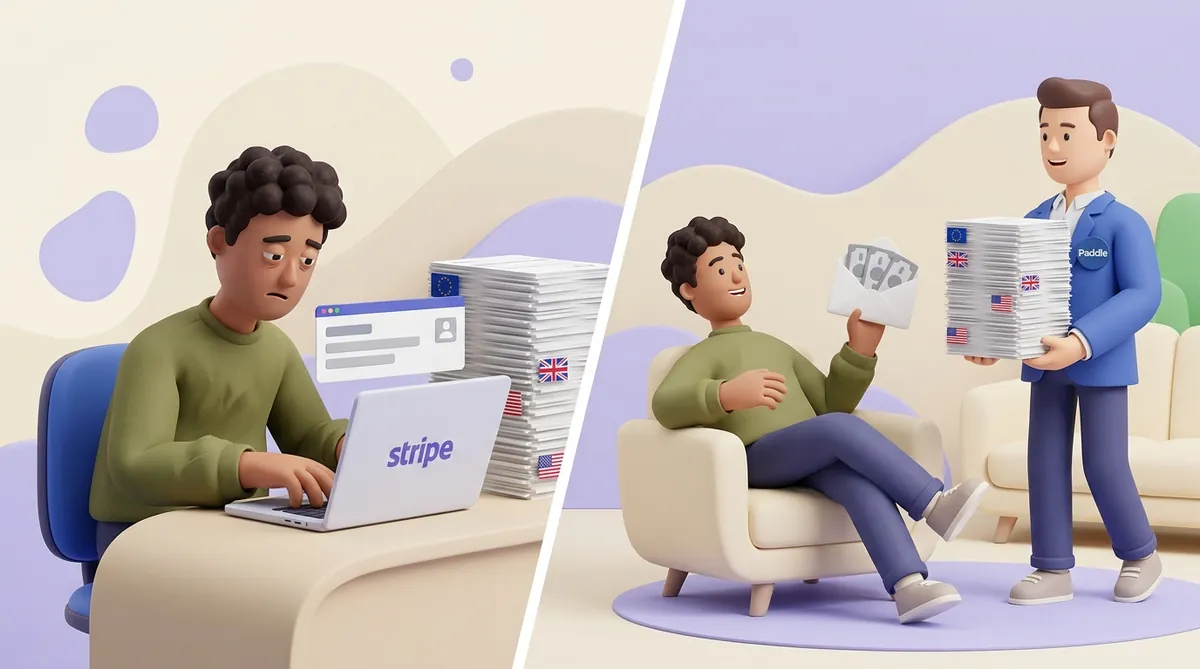
With a payment processor, you are the seller. Your company's name is on the customer's card statement, the sale is between you and the customer, and every tax obligation in every country is yours.
With a merchant of record, another company is the seller. It resells your software to the customer under its own name, collects and pays the tax in each country, and handles chargebacks, the disputes where a customer asks their bank to reverse a charge. Then it sends you what is left. Paddle, Lemon Squeezy and FastSpring work this way, and Stripe now sells the same model under the name Managed Payments.
The two models differ in three places:
Percentages are easier to judge on one real payment. Take a $50 monthly plan sold by a US company to a customer in Germany who pays in euros. Here is what each side keeps, before tax, on their US price lists as of September 2026:
Now the same plan bought by a US customer with a US card. Stripe comes to about $2.35 with Billing and Tax, and Paddle stays at $3.00.
So a processor is clearly cheaper mainly at home. On foreign cards the gap closes, and Stripe's figure still leaves out registering in other countries and filing returns there. Stripe accounts outside the US have their own price lists, so run the same sum with yours.
That sum also assumes both services take sellers from your country. In a comparison of 40 countries, Stripe works in 25 and in none of the CIS, the Caucasus and Central Asia, while Paddle, as a merchant of record for software, works in 38. Before you compare prices, check where Stripe, Paddle and seven other payment services accept sellers.
There is no single best one. There is a best fit for your customers, and it usually falls into one of two cases:
Two situations sit between those cases:
Often yes, and earlier than most founders expect. Here is how it works in the two biggest markets as of September 2026:
With a merchant of record, all of this is its job, and its fee covers it. With a processor, it is yours. Stripe Tax calculates the right rate for each customer and warns you as you approach a threshold, but the registrations and the returns stay in your company's name.
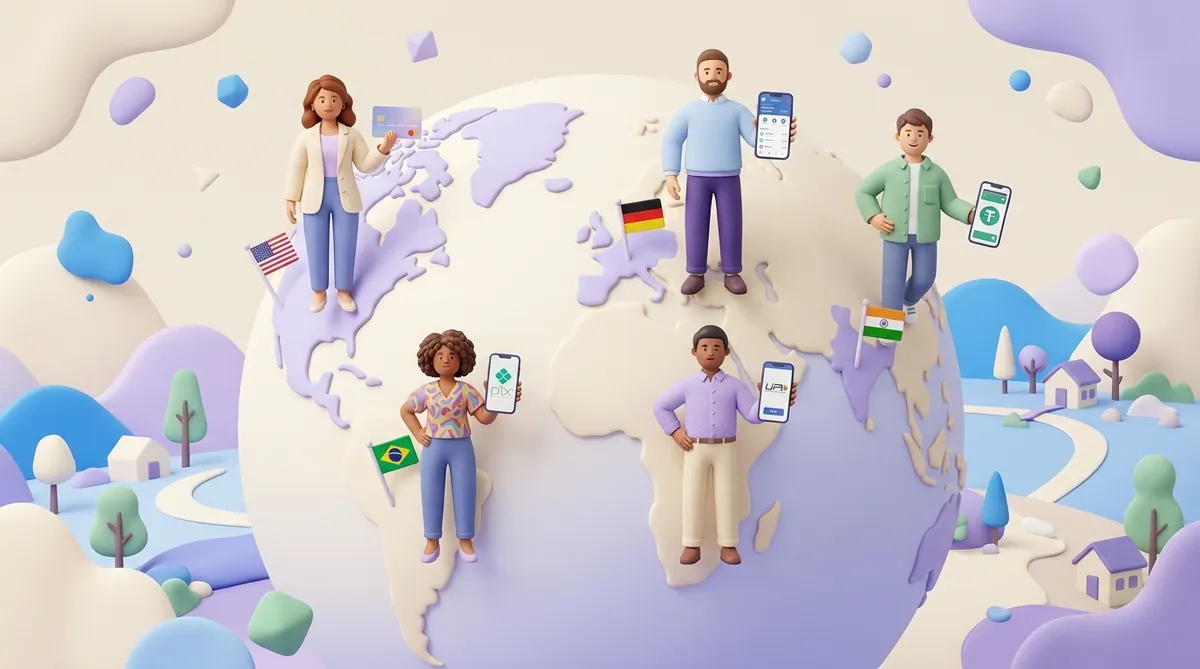
Cards work almost everywhere, but they are not everyone's first choice. What customers look for at checkout depends on where they are and who they are:
A wire from another country can take several days and lose part of its value to bank fees along the way. If you are weighing that against a stablecoin invoice for the same customers, it helps to see how crypto payments compare with bank transfers on fees and speed.
PayPal needs one more note, because so many customers already have an account. A US business can now also let customers pay in crypto through PayPal itself, and here is what accepting crypto through PayPal involves and why it is limited to US businesses.
Not every provider supports every method, and a merchant of record supports only the ones it has chosen. Before you sign, check that the methods of your two or three biggest markets are on its list.
Stripe opens accounts for businesses in about 50 countries. If yours is not among them, there are three usual routes:
Sometimes the problem is wider than Stripe: the money from customers abroad does not come in at all, whatever you try. That case has its own set of answers in how to receive payments from customers abroad when cards and transfers fail.
Yes. A stablecoin is a crypto coin whose price is tied to the dollar, so a $50 plan paid in USDT, the most widely used stablecoin, is still $50 when it arrives. It suits customers the card or the bank doesn't serve, such as a team in a country where international cards keep getting declined.
Stablecoins work as an extra method next to cards, not instead of them. Three things change compared with a card:
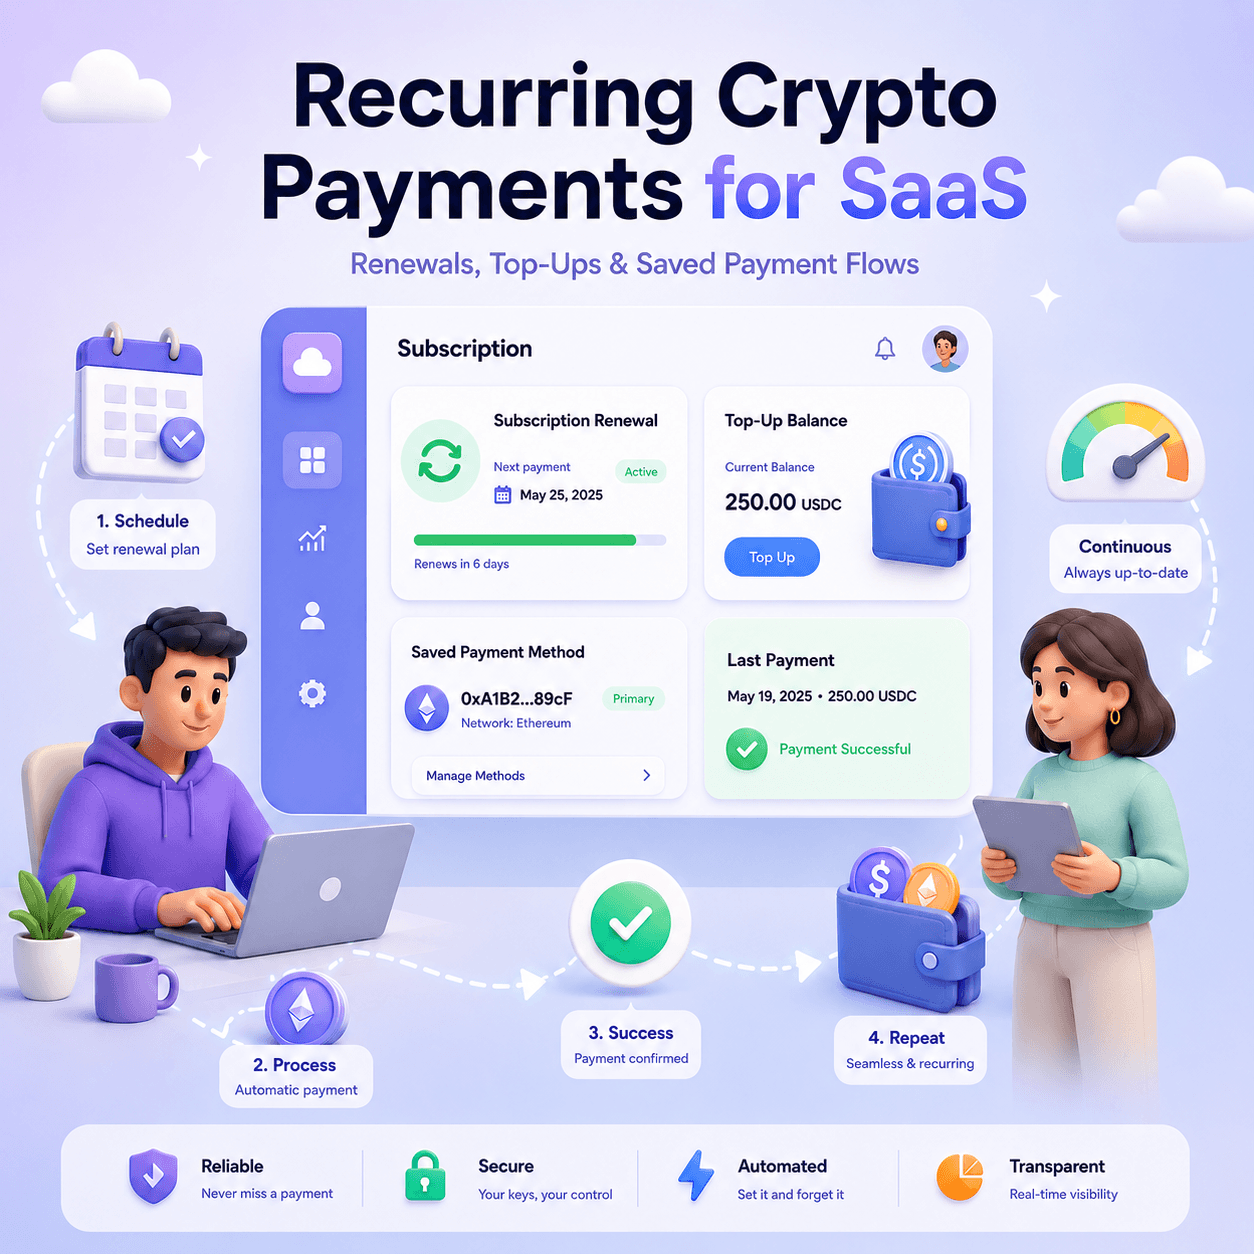
The first point is the one SaaS founders ask about most, because it changes how a subscription renews. The renewals and top-ups themselves are covered in how recurring crypto payments work for SaaS.
Between the customer's wallet and your billing system sits a crypto payment processor, which tells your billing system when a payment has arrived. CryptumPay is one built for SaaS: you add crypto next to your cards through a payment link, a checkout widget or an API, and a customer your card processor can't serve can still pay you. The customer pays from the crypto wallet they already use, needs no account or app, and whatever coin they pay in is converted, so you always receive USDT.
At CryptumPay, the fee is 1% per successful payment, down to 0.5% at higher volumes, and project review usually takes one business day. The customer confirms each renewal in their wallet, and your server gets a callback, an automatic message, when the payment arrives. The fees, the ways to connect and the review are laid out on the page about adding crypto payments to a subscription business.
If your company or your customers are in the EU, one more rule applies. MiCA, the EU's crypto regulation, has governed stablecoins since 30 June 2024, and it affects which stablecoins a business in Europe can accept in 2026.
Once revenue arrives in USDT, some companies don't convert all of it. They pay contractors and suppliers abroad in the same coin, which is a question of its own: paying suppliers abroad in stablecoins.
Most international SaaS companies end up with a main option and one or two additions. The common set-ups look like this:
The first decision is who is the seller. A merchant of record costs more per payment and takes tax off your hands; a payment processor costs less and leaves tax with you. On foreign cards the price gap is smaller than it looks.
Then look at your customers, not at the providers. Add the methods your biggest markets actually use, bank transfer for enterprise invoices, and stablecoins for the people the card or the bank can't reach.
Published rates start at around 5% plus a fixed fee per payment, and the providers price it in different ways:
For very cheap products, Paddle offers custom pricing, because a fixed 50¢ eats a large share of a $3 payment.
Paddle pays out once a month: payouts go out between the 2nd and the 15th and take up to three working days to arrive. The minimum balance is $100, adjustable up to $100,000, and a smaller balance rolls over to the next month. Money goes by wire transfer or Payoneer, and for some countries a $15 SWIFT fee applies, so check what Paddle says about your country before you integrate.
Yes, if you turn on Stripe Tax: it works out VAT, sales tax and GST for each customer from their location and the product type, and tracks your sales against registration thresholds. On the US pay-as-you-go plan it costs 0.5% per transaction where you are registered if you use it through Stripe's own tools such as Billing, Checkout or Payment Links, and 50¢ per transaction through the Tax API. Stripe can also register you for US sales tax and handle filing directly or through partners, but you remain the seller and the obligation stays yours.
Yes. As of September 2026 the standard UK VAT rate is 20%, and it applies to software sold to UK consumers. A business based outside the UK must register for UK VAT from its first sale to UK consumers; the £90,000 registration threshold applies only to UK-based businesses. Sales to UK VAT-registered businesses are normally handled by the customer under the reverse charge.
The billing system tries again: Stripe's Smart Retries choose when to repeat the charge, Paddle includes failed-payment recovery, and both can email the customer to update the card. If the retries fail, the subscription is marked past due and then cancelled or left unpaid, depending on your settings. A crypto renewal is never declined in this sense, but it can still fail on the customer's side, and the usual causes are covered in why crypto payments fail and how to reduce failures.
This article is general information and not legal or tax advice. Tax rules depend on where your company and your customers are, so check your situation with a qualified adviser.
Create an account and connect the checkout yourself, or talk to sales and we will plan the integration with you.

