

November 10, 2024
Crypto Payment Trends 2026: Stablecoins, Regulation, x402 and Better Payment UX
Read article
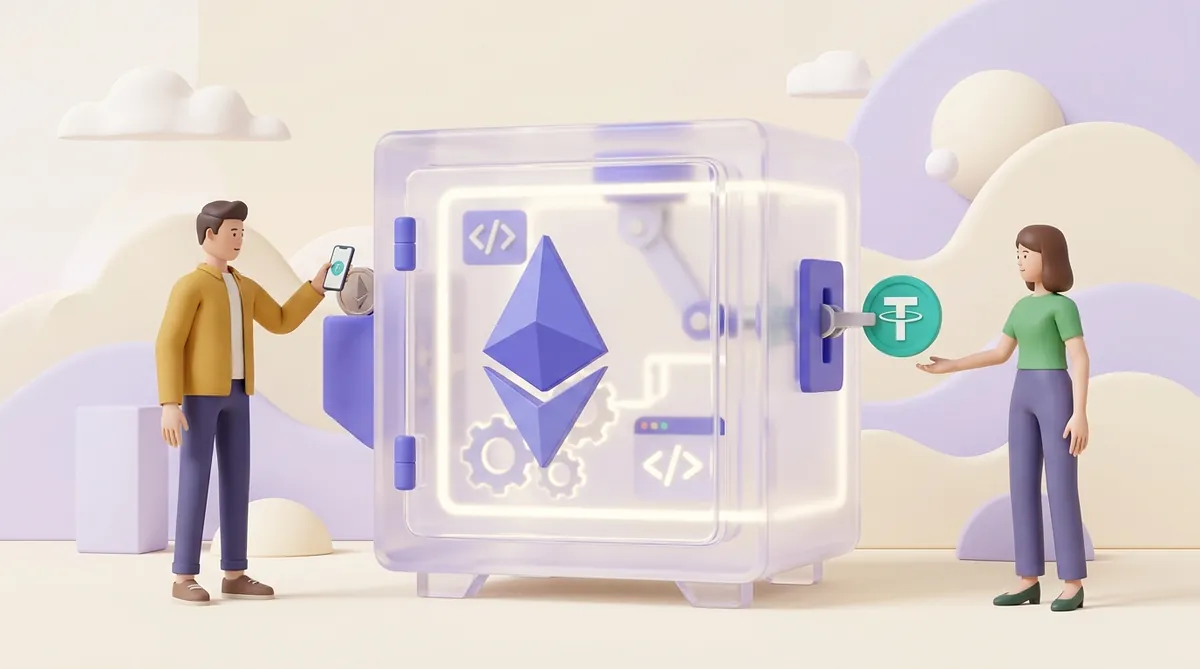
A smart contract is a program stored on a blockchain that runs by itself whenever someone sends it a transaction. Its code is public, it runs the same way for everyone, and it does exactly what that code says, which is why it can hold and move money without a middleman.
You have probably used one already: USDT on Ethereum or TRON is a smart contract that keeps everyone's balances, and every USDT transfer is a request to it.
A smart contract only makes sense on top of a blockchain: a shared record that thousands of computers keep in identical copies, so no single one of them can rewrite it. If that part is new to you, it helps to start with how cryptocurrency and the blockchain under it work.
A smart contract adds a program to that shared record. Its life has four stages:
Take a USDT transfer. Your wallet sends the USDT contract a message: move 100 USDT from me to Anna. The contract checks that your balance holds at least 100, lowers your number by 100 and raises Anna's by 100.
No bank approves that change, and it cannot stop halfway. Either the whole transfer goes through, or none of it does.
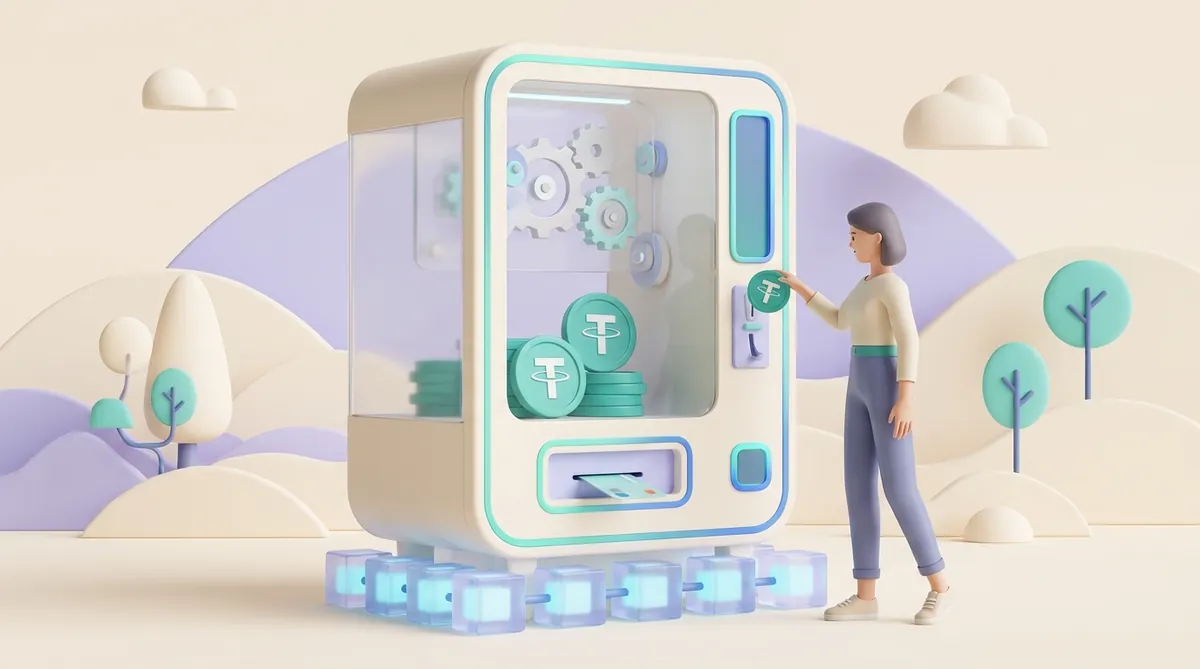
The classic comparison is a vending machine, which the computer scientist Nick Szabo used when he described smart contracts in the 1990s. Put in the right coins, press a button, and the machine hands over the snack without a cashier. A smart contract is the same kind of machine, except anyone can read its wiring and every node runs its own copy.
Despite the name, a smart contract is a program, not a legal document. It moves digital assets by rules and knows nothing outside its own blockchain, so it cannot, say, check whether a parcel has arrived.
Most of what people do in crypto beyond sending a network's own coin goes through smart contracts. The common ones:
Even the wallet itself can be a smart contract. A regular wallet obeys whoever holds its one secret key, while a contract wallet can add rules of its own, such as signing with a phone passkey instead of a seed phrase. The idea behind it is called account abstraction, and here is how smart wallets and passkeys work.
A smart contract needs a blockchain built to run programs, and not every blockchain is. The networks people meet most often:
Each of these networks keeps its own copy of popular tokens, and each charges its own fee to run contract code. A USDT balance on TRON and one on Ethereum are entries in two different contracts that know nothing about each other.
Since most smart contract terms started on Ethereum, it is the network worth understanding first. Its payment side, from a customer's ETH arriving to a seller turning it into money they can use, is covered in how to accept Ethereum payments and get the money out.
Every deployed smart contract gets an address, just like a wallet. On Ethereum and networks built like it, the address is 42 characters long and starts with 0x. The network calculates it from the creator's address at the moment of deployment, and nobody holds a private key to it: only the contract's own code decides what happens to anything sent there.
For an ordinary user, the smart contract address matters in two situations:
A block explorer such as Etherscan or Tronscan opens any contract by its address, together with its full transaction history. When you need to check where a payment went or which contract a token really belongs to, it helps to know how to read a transaction in a blockchain explorer.
A smart contract call is a transaction sent to a contract instead of to a person. Besides the address, it carries data: which function to run and with what inputs.
Explorers show that function in a "Method" column. The names you will meet most often:
Some wallets show all of this under one generic label. In Trust Wallet's history, for example, an entry can read "Smart Contract Call", often next to an amount of 0 ETH or 0 BNB. Zero is normal: the call moved none of the network's own coin and only gave an instruction, such as a swap. The network fee for it was still paid.
The call worth stopping at is Approve. The permission it grants is often for an unlimited amount, and it stays in force until you withdraw it. If you have ever connected a wallet to an exchange or a game, it is worth learning how to check and revoke token approvals.
Running code on thousands of computers costs something, so every smart contract call pays a fee. On Ethereum the work is measured in gas: each step the contract takes has a fixed price in gas units, and the fee is the gas used multiplied by the price of one unit.
The more the code does, the more gas it uses. A plain ETH transfer takes 21,000 gas. A USDT transfer runs contract code and takes roughly two to three times as much, and heavier actions cost more still.
Two rules surprise people the first time:
The price of one unit of gas is quoted in gwei, a billionth of an ETH, and it climbs when the network is busy. Since the London upgrade of August 2021, the base part of that price is burned rather than paid out, and senders can add a tip to get included sooner. How those pieces add up to the figure your wallet shows is laid out in what gwei is and how it turns into your Ethereum fee.
"Code runs exactly as written" is the strength of a smart contract and also the source of most of its problems:
No. A shop that takes USDT does not write or publish any code: the customer's wallet calls the existing USDT contract, and the tokens land at the address the shop gave. The work left on the shop's side is bookkeeping: matching each incoming payment to its order.
That bookkeeping is the job of a crypto payment gateway, which watches the blockchain for the shop and marks each order as paid once the money is in. Here is what a crypto payment gateway does for a business.
CryptumPay is one such payment service, not a wallet: it accepts payments from customers and pays out to the address the seller names. What it offers:
Whichever service a seller picks, a crypto payment carries more than one fee:
Comparing services means adding up both, and each line is broken down in how crypto payment fees work, from gas to gateway fees.
A smart contract is a program on a blockchain that holds and moves digital assets by rules anyone can read, and every node enforces those rules the same way. Most of crypto beyond plain coin transfers runs on smart contracts. For everyday use, three habits matter most:
No. Bitcoin is a currency on its own blockchain, and its scripting language is deliberately simple. It can require several signatures or lock coins until a set time, but it cannot run general programs the way Ethereum does, so smart contracts in the full sense live on networks built for them.
You can trust a smart contract to do what its code says, which is not the same as trusting it to be safe. The practical test is who can still change the rules: open the contract in a block explorer, and if its code is unpublished or an owner can upgrade it at will, you are trusting that owner rather than the code. Audits lower the risk but do not remove it, because audited contracts have been hacked too.
No. A regular contract is an agreement between people that courts can enforce; a smart contract is code that enforces itself, and only inside its own blockchain. The two can be combined: in England and Wales, the Law Commission concluded in its advice of 25 November 2021 that existing law can already support smart legal contracts, where some terms are carried out by code, without new legislation. In other countries the answer depends on local law.
Open the transaction in a block explorer and look at the "From" field. If it shows someone else's address, another person's transaction touched yours, which is often spam: scammers send worthless tokens or fake transfers so that a look-alike address appears in your history and gets copied by mistake later. If it shows your own address, you signed that call, and it is worth checking what it approved.
This article is for general information only and is not legal advice.
Create an account and connect the checkout yourself, or talk to sales and we will plan the integration with you.